

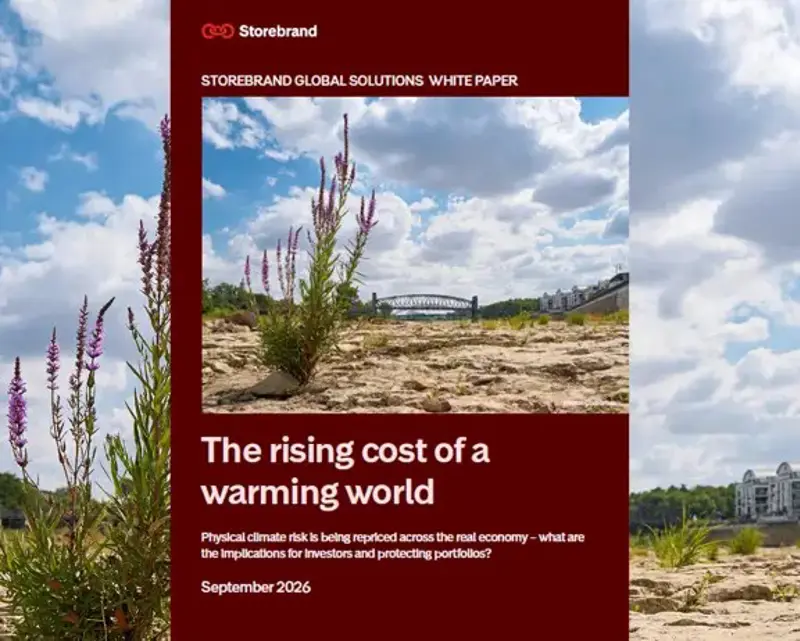
Western Europe has just lived through its hottest summer since records began. June and July averaged 21.6°C, close to three degrees above the long-run average and (un)comfortably hotter than the previous record set only four years ago. It was also not an isolated spike; an unusually early heatwave in May was followed by a series of further hot spells into August, accompanied across much of the continent by wildfires and drought.
The extreme temperatures were also widespread. France recorded its hottest national average day ever when temperatures hit 30⁰C in June, records fell for three consecutive days in Germany when 46 locations exceeded 40⁰C in the same month and Spain endured persistent highs above 42⁰C. The hot weather also had a significant human cost with early estimates suggesting that Europe’s four back-to-back heatwaves contributed to at least 35,000 excess deaths over the summer[1].

The record-breaking temperatures also had an unprecedented economic impact. The Rhine fell to its lowest recorded level at Cologne that saw barge traffic on one of Europe's busiest freight corridors slow to a crawl. Low and warming rivers forced nuclear plants in Hungary and Romania to cut output as reactors were unable to discharge waste heat safely at full capacity, and grain harvests in France and elsewhere came up short.
Clear and present danger
For most of the last decade, climate risk has typically been discussed as something that arrives around 2050 and is expressed in percentage points of global GDP, rather than an immediate monetary cost. The effects of this summer, however, have been felt almost immediately and by all of us in the form of higher freight rates, power prices and food costs.
Indeed, the evidence of recent years is that the physical cost of a warming climate has stopped being a forecast and is already embedded in insurance premiums, mortgage delinquencies, transportation rates and even the price of a bar of chocolate. Physical climate risk is being repriced across our economy faster and in more places than ever before – all regions, sectors and asset classes face some level of exposure.
For investors, who have traditionally focused on market, credit and liquidity risks in security and portfolio analysis, climate-related threats are now a clear and present danger. Rising insurance, food, transport and energy costs are impacting mortgage books, municipal budgets, corporate earnings and headline inflation.
Investable solutions
Thankfully for investors, these pressures are also creating a large, growing and increasingly investable market for solutions that can help alleviate them. Protecting the traditional economy we already have and building the lower-carbon one we increasingly need requires huge capital expenditure and investment is running at record levels. Total spending on the energy transition alone reached around US$2.3 trillion in 2025, more than double the level of 2020.
This paper looks at the rising costs of a warming world and, using examples from our portfolio, how solutions companies are meeting the challenges created by a climate that has already changed. It will explore four main areas where climate-related costs are increasingly measurable – insurance, housing, food, and energy and transport – and trace their portfolio impact through credit, earnings and inflation effects. Importantly, it will also pair each of these areas with a theme from our portfolio that helps address these downside risks.
You can read the full white paper here.
-----
[1] The Guardian, August 2026